 Google AI
 ChatGPT
 Perplexity
What is Halal Real Estate Investing in the U.S.? It’s the acquisition, ownership, and management of property using Sharia-compliant financial instruments. These instruments avoid Riba (interest), excessive risk (Gharar), and prohibited sectors like alcohol or gambling.
Instead of conventional interest-based mortgages, Halal investing relies on profit-sharing or lease-to-own models. This keeps your wealth-building aligned with Islamic financial principles.
The Halal Path to American Property Ownership
Are you an American Muslim investor struggling to find real estate that matches your faith? The mainstream market runs on Riba (interest) and non-compliant deals. Growing wealth without compromising your values can feel impossible.
You need a trusted, transparent, Sharia-compliant path. As the Quran states, “Allah has permitted trade and forbidden Riba” (Surah Al-Baqarah, 2:275).
This guide gives you a clear, step-by-step roadmap for investing in Halal real estate in the U.S. — one that protects both your capital and your spiritual commitments.
U.S. Muslims hold an estimated $170 billion in liquid assets. Homeownership remains central to the American dream, so demand for Islamic home financing is booming. This is drawing more specialized firms into the space, making ethical investment more accessible than ever.
This is your essential resource to becoming a successful, Sharia-compliant real estate investor in America.
Understanding the Halal Difference: Why Sharia Compliance Matters
Sharia compliance isn’t just a religious formality. It’s an ethical framework built on stability, fairness, and shared risk.
For Muslim investors, following these rules means wealth is built through permissible means — protecting spiritual commitments while still pursuing property ownership.
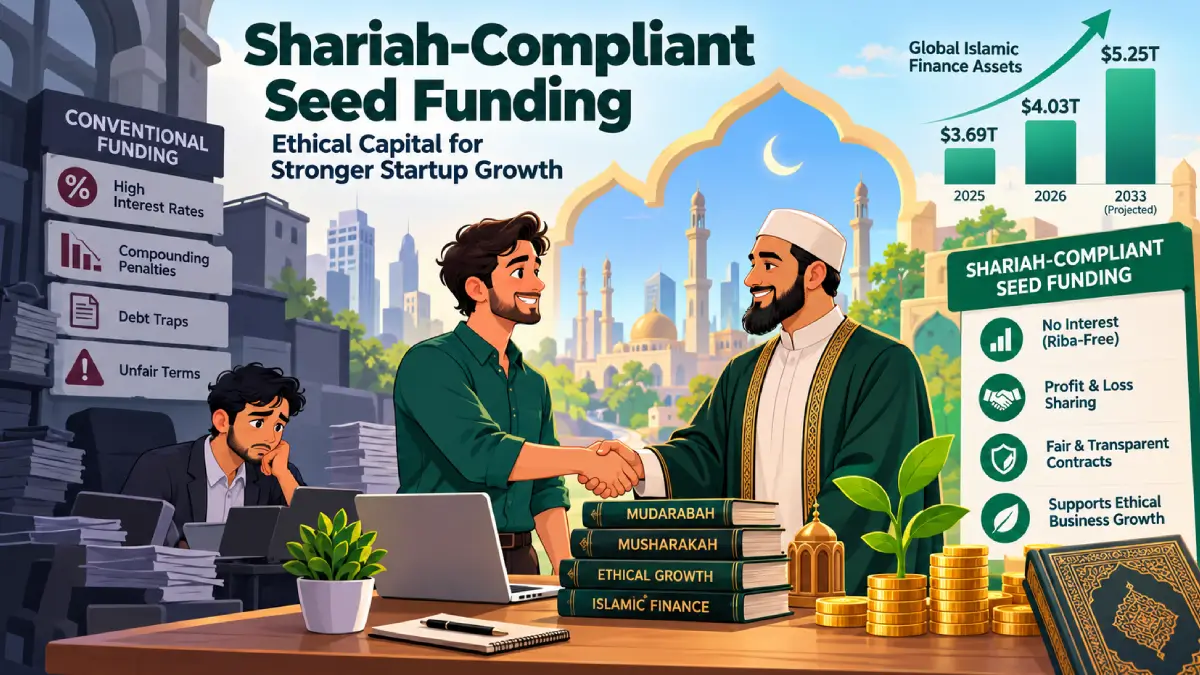
The core shift is moving from a debt-based system that favors creditors to an equity- and partnership-based system that shares both profit and loss. This reflects the principle of Tawhid (unity of God) by promoting justice in financial dealings.
The Core Prohibitions: Riba, Gharar, and Maysir
Riba (Interest/Usury)
Riba means “excess” or “increase.” It’s the most critical prohibition — any predetermined, fixed return charged for the use of money.
Why it’s forbidden: Islam treats money as a medium of exchange, not a commodity to profit from directly. Charging interest lets the lender earn a return without taking on real risk, shifting all the risk to the borrower.
The Quran warns clearly against this: “O you who have believed, fear Allah and give up what remains [due to you] of Riba if you should be believers” (Surah Al-Baqarah, 2:278).
In a conventional mortgage, interest stays due even if the property loses value or the investor takes a loss. That’s exactly what’s prohibited.
Gharar (Excessive Uncertainty) and Maysir (Gambling/Speculation)
Gharar means excessive or unclear risk — where a transaction’s terms are ambiguous, risking unfair gain for one side.
In real estate, this covers highly speculative deals, complex derivatives tied to property values, or contracts with vague terms on ownership or payments. Sharia-compliant contracts need clear terms: assets, prices, and delivery dates.
Maysir bans any transaction that resembles gambling — where gain depends purely on chance, not productive effort.
In real estate, this includes buying property purely for rapid speculation with no added value, or using leveraged products that act like bets on market movement rather than real ownership.
Comparing Halal vs. Conventional Financing
| Feature | Conventional Financing (Mortgage) | Halal Financing (e.g., Murabaha/Musharaka) |
| Core Structure | Debt-based loan with fixed interest (Riba) | Asset-based sale (Murabaha) or Equity Partnership/Lease (Musharaka/Ijarah) |
| Lender’s Role | Creditor (Lender) | Seller/Partner/Lessor |
| Payment Structure | Interest + Principal, paid regardless of performance | Profit-Sharing (Musharaka), Fixed Mark-up (Murabaha), or Rent (Ijarah) |
| Risk Bearing | Borrower bears most risk; lender’s return is guaranteed | Risk shared based on ownership/partnership equity |
| Ownership | Borrower owns immediately, bank holds a lien | Ownership transfers gradually or upon final payment |
The Halalvest Solution: A Trusted Alternative
Comparing halal vs. conventional real estate loans in the US can get complicated. Halalvest structures Sharia-compliant models with transparent, verified financing — so you can invest ethically and securely in U.S. property.
The Step-by-Step Halal Investment Roadmap
Investing in Halal real estate takes a disciplined approach — combining financial planning with Sharia compliance checks at every stage. Here’s a clear, actionable roadmap.
Step 1: Setting Your Financial and Spiritual Goals
Start with clarity on what you want.
Define your investment horizon and risk tolerance:
- Decide if you want short-term capital gains (flipping via Murabaha, or a quick sale of a jointly owned asset) or long-term passive income (rental income via Ijarah or Musharaka).
- Match your risk tolerance to the right structure. Partnership models (Musharaka) offer higher potential rewards but also higher risk than fixed-markup sales (Murabaha).
Verify the need for Sharia certification:
Every investment — the asset, the financing instrument, and the business purpose — must be screened and certified by a recognized Islamic scholar or Sharia Board.
Step 2: Finding Sharia-Compliant Opportunities
Finding Sharia-compliant real estate in a mostly conventional U.S. market is a real challenge.
- The challenge: Mainstream listings don’t filter for Sharia-compliant criteria. Sourcing compliant deals takes specialized effort.
- Niche resources: Use platforms and networks built for ethical investors. Halalvest runs a proprietary network of brokers sourcing pre-vetted, Sharia-certified opportunities across the U.S. — saving you the compliance-verification legwork.
- Look for properties in communities with existing demand for Halal financing. This often leads to better deal flow.
Step 3: Exploring Halal Financing Options in the U.S.
Forget conventional “loans.” Halal investing replaces interest with sale or partnership agreements.
| Financing Structure | Core Mechanism | Property Use |
| Murabaha (Cost-Plus Financing) | Financier buys the asset, resells at a fixed mark-up, paid in installments | Residential purchases or short-term financing |
| Musharaka Mutanaqisah (Diminishing Partnership) | Financier and client are partners; client buys out the financier’s share over time | Long-term residential and commercial ownership |
| Ijarah (Leasing) | Financier buys and leases the asset for fixed rent, with ownership transfer at term end | Commercial real estate and equipment |
Step 4: Due Diligence and Structuring the Deal
The final step needs specialized legal and financial review.
Due diligence for Halal deals goes beyond standard financial checks. You need a legal team that understands both U.S. property law and Sharia contract law.
- They must ensure the agreement is a genuine sale or partnership — not a conventional loan wearing a Halal label.
- Getting this wrong can nullify the deal’s Halal status.
Always obtain and review the official Sharia certification for the specific transaction and financing entity. This is your guarantee of spiritual safety.
Key Sharia-Compliant Investment Models Explained
Halal real estate investing moves past the conventional debt-for-interest model. It’s built on profit/loss sharing and asset-backed transactions. Understanding these models shows Halalvest’s commitment to verifiable Sharia-compliant principles.
The Partnership Models: Musharakah and Mudarabah
These structures embody the core Islamic finance principle: risk-sharing.
- Musharakah (Joint Ownership/Partnership): Two or more partners contribute capital to a venture. Profits split by a pre-agreed ratio. Losses split strictly by capital contribution. Diminishing Musharakah is the most common form for home financing — the client gradually buys out the financier’s share.
- Mudarabah (Profit-Sharing/Labor-Capital Partnership): One party (Rab-ul-Maal) provides all the capital. The other (Mudarib) provides labor and expertise. Profits are shared by agreement. If a loss occurs without the Mudarib’s negligence, the capital provider bears it alone.
Residential Fix & Flip (Hybrid Musharakah + Mudarabah): The investor provides capital while Halalvest manages the renovation and sale as the Mudarib. Or both sides contribute capital (Musharakah), with Halalvest providing expertise and profits split by agreement.
Condominium Development (Hybrid Istisna + Musharakah): Initial construction runs through an Istisna contract. Land acquisition and unit sales run through a Musharakah joint venture between the developer, financial institution, and end-buyers.
The Lease-Based Model: Ijara
Ijara (Leasing/Renting) means “to give something on rent.” The financier (lessor) buys the asset and leases its use to the client for a fixed rent. The lessor keeps ownership and handles major maintenance; the lessee covers day-to-day upkeep.
Ijara Muntahia Bi Tamleek (Lease-to-Own) is the most popular form for residential use. It pairs two contracts: a lease (Ijara) and a separate promise to sell or gift the asset at the end of the term. This avoids the conditional-sale structure that conventional finance often uses.
Apartment Building Acquisition (Ijara Muntahia Bi Tamleek): Halalvest buys the building and leases it to the client entity. Rent payments gradually reduce the lease obligation. Title transfers on the final payment.
Medical Office Space (Ijara – Option to Buy): Halalvest leases the property to a tenant (e.g., a medical practice) for a fixed term. The lease may include a separate option letting the lessee buy the property at a set price at term end.
The Sale-Based Models: Murabaha and Istisna
Murabaha (Cost-Plus Financing): A sales contract, not a partnership. The financier buys the asset the client wants, then immediately resells it at cost plus a fixed, transparent markup — paid in installments. The price is fixed and can’t change, which protects the buyer from Riba.
Istisna (Manufacturing/Construction Contract): A contract to sell something that’s manufactured, constructed, or delivered after the contract starts. Price and specs are fixed upfront. This is the primary tool for financing construction, since the asset doesn’t exist yet.
Suburban Duplex Build (Hybrid Istisna + Murabaha): Halalvest uses an Istisna contract to finance construction, paying the builder by milestone. Once complete, Halalvest sells the duplex to the client via Murabaha — cost plus markup, paid over time.
Advanced Investment Strategies for the U.S. Muslim Investor
Sophisticated investors can go further — using complex, Sharia-compliant structures to access institutional-grade assets while staying compliant.
Navigating Halal Real Estate Investment Trusts (REITs)
Are REITs halal for American Muslim investors? Often yes — but with strict requirements.
REITs let you invest in large, diversified real estate portfolios without direct ownership hassle. But conventional REITs are often non-compliant due to high leverage and non-permissible tenants (casinos, bars).
Rigorous Sharia screening applies two tests:
- Business Test: Core operations must be permissible. Non-Halal income must stay below a de minimis threshold — typically 5%.
- Financial Test: Interest-bearing debt must stay below a set ratio, often 33% of asset market value, per boards like AAOIFI.
A private real estate fund can also be structured as a Musharakah from the ground up. This avoids high leverage and makes the fund a true partner — sharing risk and return with the investor.
REIT + Musharakah (Mixed-Use Multifamily REIT): Halalvest structures closed-end funds as a Musharakah to acquire and manage U.S. multifamily and commercial properties. The investor is a partner. Profits come from realized rental income and appreciation — no conventional interest-based financing involved.
Exploring Niche and Alternative Halal Assets
Moving beyond residential offers diversification and higher return potential:
- Commercial and Industrial (Warehouses/Logistics): Typically leased via Ijara, providing steady rental income. Permissible business use simplifies Sharia screening.
- Land and Farmland: Highly desirable since it’s a tangible, productive asset. Financing works via Murabaha (immediate sale) or Musharakah (farming/development partnerships) — aligned with Islam’s emphasis on real wealth creation.
Tax and Legal Considerations
Halal real estate deals still operate fully within U.S. legal and tax rules — and they’re worth getting professional advice on.
Structures like Murabaha and Musharakah are treated as “lease-purchase” or “partnership” agreements for Sharia purposes, but the IRS may treat them differently for income, property, and transfer tax.
Key areas:
- Depreciation: Investors can generally claim depreciation over 27.5 years (residential) or 39 years (commercial).
- Deductions: Property taxes, insurance, and maintenance are typically deductible against rental income.
- Profit-sharing vs. interest: A tax advisor should confirm the “profit share” or “rental rate” is treated correctly by the IRS — often deductible as imputed interest or rent.
Choosing the Right Location for Halal Investment
Location choice should weigh both market fundamentals and the local Muslim community.
The best cities for Halal property investment often have large, established Muslim populations — Houston, Dallas, Chicago, Northern Virginia, parts of New Jersey.
- Benefit: High Muslim population density means strong local demand for Halal financing and housing.
- Local compliance: These cities usually have accessible Islamic financial institutions, specialized brokers, and scholars for easy compliance checks.
The Challenges and Benefits of Halal Homeownership and Investment
The path to Sharia-compliant wealth is ethically rewarding, but it comes with practical trade-offs in the U.S. market.
Overcoming Challenges to Halal Homeownership
Limited providers and availability: The U.S. Islamic finance industry is still small. Fewer providers mean less competition, which can raise costs. Most genuine Musharakah or Ijara providers are specialized non-bank institutions or “Islamic windows” navigating complex regulation.
Less flexibility and higher costs:
- “Piety premium”: Higher legal, compliance, and Sharia Board oversight costs — plus genuine risk-sharing — can make Halal financing pricier than conventional mortgages.
- Less flexibility on terms: Since contracts are sales or partnerships with fixed terms, early debt retirement or refinancing may need re-contracting under Sharia principles.
The Benefits of Choosing Sharia-Compliant Real Estate Funds
The benefits outweigh the ethical cost of going conventional:
- Ethical peace of mind: Avoiding Riba and Gharar means your wealth-building aligns with your faith — often called a “piety premium” worth paying.
- Stability and asset-backed security: Halal investments are tied to tangible real estate, not volatile debt instruments — offering more stability.
- Shared risk and partnership: Models like Musharakah require genuine risk-sharing. The financier is a partner, not a guaranteed-return lender — a more equitable relationship.
- Positive social impact: Sharia-compliant finance tends to favor community development and ethical industries.
Partnering with Halalvest: Your Trusted Path to Compliant Wealth
You don’t have to choose between faith and financial future. Halalvest bridges ethical investing and high-performing U.S. real estate.
Why Halalvest Stands Out
- Trust and authority: A network of 1,000+ active traditional partners — licensed brokers, property managers, legal professionals — ensures high standards and smooth execution.
- Superior value: Our deal-sourcing methods acquire investment-grade properties at 20% to 50% below market value. This built-in equity cushion maximizes returns and limits downside risk.
- Deep expertise and compliance: We structure complex Islamic finance contracts and ensure U.S. regulatory compliance. Every step — acquisition, financing, exit — is certified by an independent Sharia advisory board.
See Our Investment Models in Action
Review our current opportunities to see the security and profitability of Sharia-compliant real estate — from long-term rental income through Ijara funds to high-growth Musharakah development partnerships.
Ready to move from learning to earning? Explore our current portfolio offerings and secure your share in a genuinely Sharia-compliant U.S. property today.
Conclusion: Secure Your Ethical Financial Future
Investing in Halal real estate in the U.S. isn’t a compromise — it’s a superior strategy for stable, ethical, high-potential wealth building.
Using models like Musharakah and Ijara ties your capital growth to tangible assets, genuine partnership, and shared risk. You get the confidence of avoiding Riba and Gharar, while securing both your financial future and your faith.
This guide has given you the roadmap. Now it’s time for action. Don’t let Riba hold back your financial future — take the first step toward securing your capital by joining the Halalvest platform today.
FAQs
1. How does the IRS treat the “profit payments” in an Islamic financing contract? Are they tax-deductible like conventional mortgage interest?
The IRS doesn’t treat Sharia-compliant payments (Musharakah or Ijara) as interest, since the transaction is structured as a partnership or lease-to-own. But the industry has worked to get the financier’s profit portion treated as “imputed interest” for tax purposes — often allowing a deduction similar to the conventional mortgage interest deduction, with the right documentation. Consult a tax professional familiar with these structures.
2. What additional costs, such as Sharia Board fees, are involved in closing a Halal real estate deal?
Expect a few extra costs beyond conventional deals: Sharia Board certification fees for approval and audits, higher legal fees for drafting multiple contracts (like sale and lease contracts for Ijara), and potentially higher closing costs from registering dual ownership in a Musharakah.
3. Is it permissible in Islam to invest in raw, undeveloped land in the U.S. for speculation or profit?
Yes, generally — since it’s a tangible asset. But intent matters: avoid Maysir (pure speculation). Holding land for a quick flip with no productive effort can be problematic. The most solidly compliant approach is acquiring land for a productive purpose — development via Istisna, or agricultural use.
4. What happens to the property if a Halal financing client defaults on their payments? Is the process different from a conventional foreclosure?
Yes, very different — because of risk-sharing. In a Diminishing Musharakah, the financier is a partner, not a lender. If the client defaults, the asset is sold and proceeds split by current equity shares. Conventional foreclosure prioritizes the lender’s debt recovery first, often leaving the homeowner with little equity. The Halal model aims for a fairer split of losses.
5. Which U.S. states are considered the most supportive or have the highest availability of Halal home financing providers?
Providers concentrate where Muslim communities are large and demand is high: California, Texas (Houston, Dallas/Fort Worth), New Jersey, New York, Illinois (Chicago), Michigan, and Virginia. Major providers like UIF Corporation and Guidance Residential operate across multiple states, but service quality is strongest in these hubs.
About the Editor
Mufti Qari Muhammad Jehangir TareenMufti Qari Muhammad Jehangir Tareen is a respected Islamic scholar specializing in Shariah compliance, Islamic finance, and the application of classical jurisprudence to modern investment structures. He has extensive experience reviewing real estate investment models and educational content to ensure alignment with Islamic principles. His work emphasizes the avoidance of riba, excessive gharar, and maysir, while promoting asset-backed, transparent, and ethical risk-sharing frameworks. Mufti Jehangir is well-versed in Shariah-compliant structures such as Musharakah, Mudarabah, Murabaha, Ijara, and Istisna. His reviews focus on proper contractual execution and clear communication to avoid any implication of guaranteed returns. And Allah knows best.